Key takeaways:
Learning how do foreclosure auctions work involves understanding the 90 to 120 day initiation timeline and the crucial 5% to 10% deposit requirements during bidder registration. The process includes live bidding that often starts at the amount owed to the lender, with payment due typically within 48 hours. Post-sale, a redemption period lasting up to 12 months may delay final ownership transfer, affecting purchase certainty.
What if winning a foreclosure auction does not guarantee immediate ownership? Many buyers underestimate the impact of the redemption period and necessary due diligence on liens and occupancy risks when exploring foreclosure sales. Understanding the nuances of title checks and auction payment rules can save substantial time and money. Knowing these details lets you navigate the foreclosure auction landscape with confidence and strategic insight.
How Do Foreclosure Auctions Work: Key Stages
Initiation: Notice and Timeline
The foreclosure auction process begins with the lender issuing a formal notice of default or foreclosure. This notice alerts the homeowner that they have missed mortgage payments and that the property will be sold at auction to satisfy the debt. The notice typically initiates a timeline that varies by state but often lasts between 90 and 120 days before the auction date. This timeline allows homeowners some chance to catch up on payments or redeem the property.
During this initiation stage, the lender files public documents that provide the official auction date, time, and place. Understanding these key documents and the timeline gives buyers a clear idea of when the property will come up for sale and how much time remains to prepare. Knowing average waiting periods helps bidders plan when to register and attend the auction.
Auction Day Process: Registration, Bidding, Payment
On auction day, the process starts with bidder registration. Typically, you must show valid ID and provide a deposit—usually between 5% and 10% of the property’s estimated value—often in the form of a cashier’s check or certified funds. This deposit confirms serious intent and guarantees funds for the auctioneer.
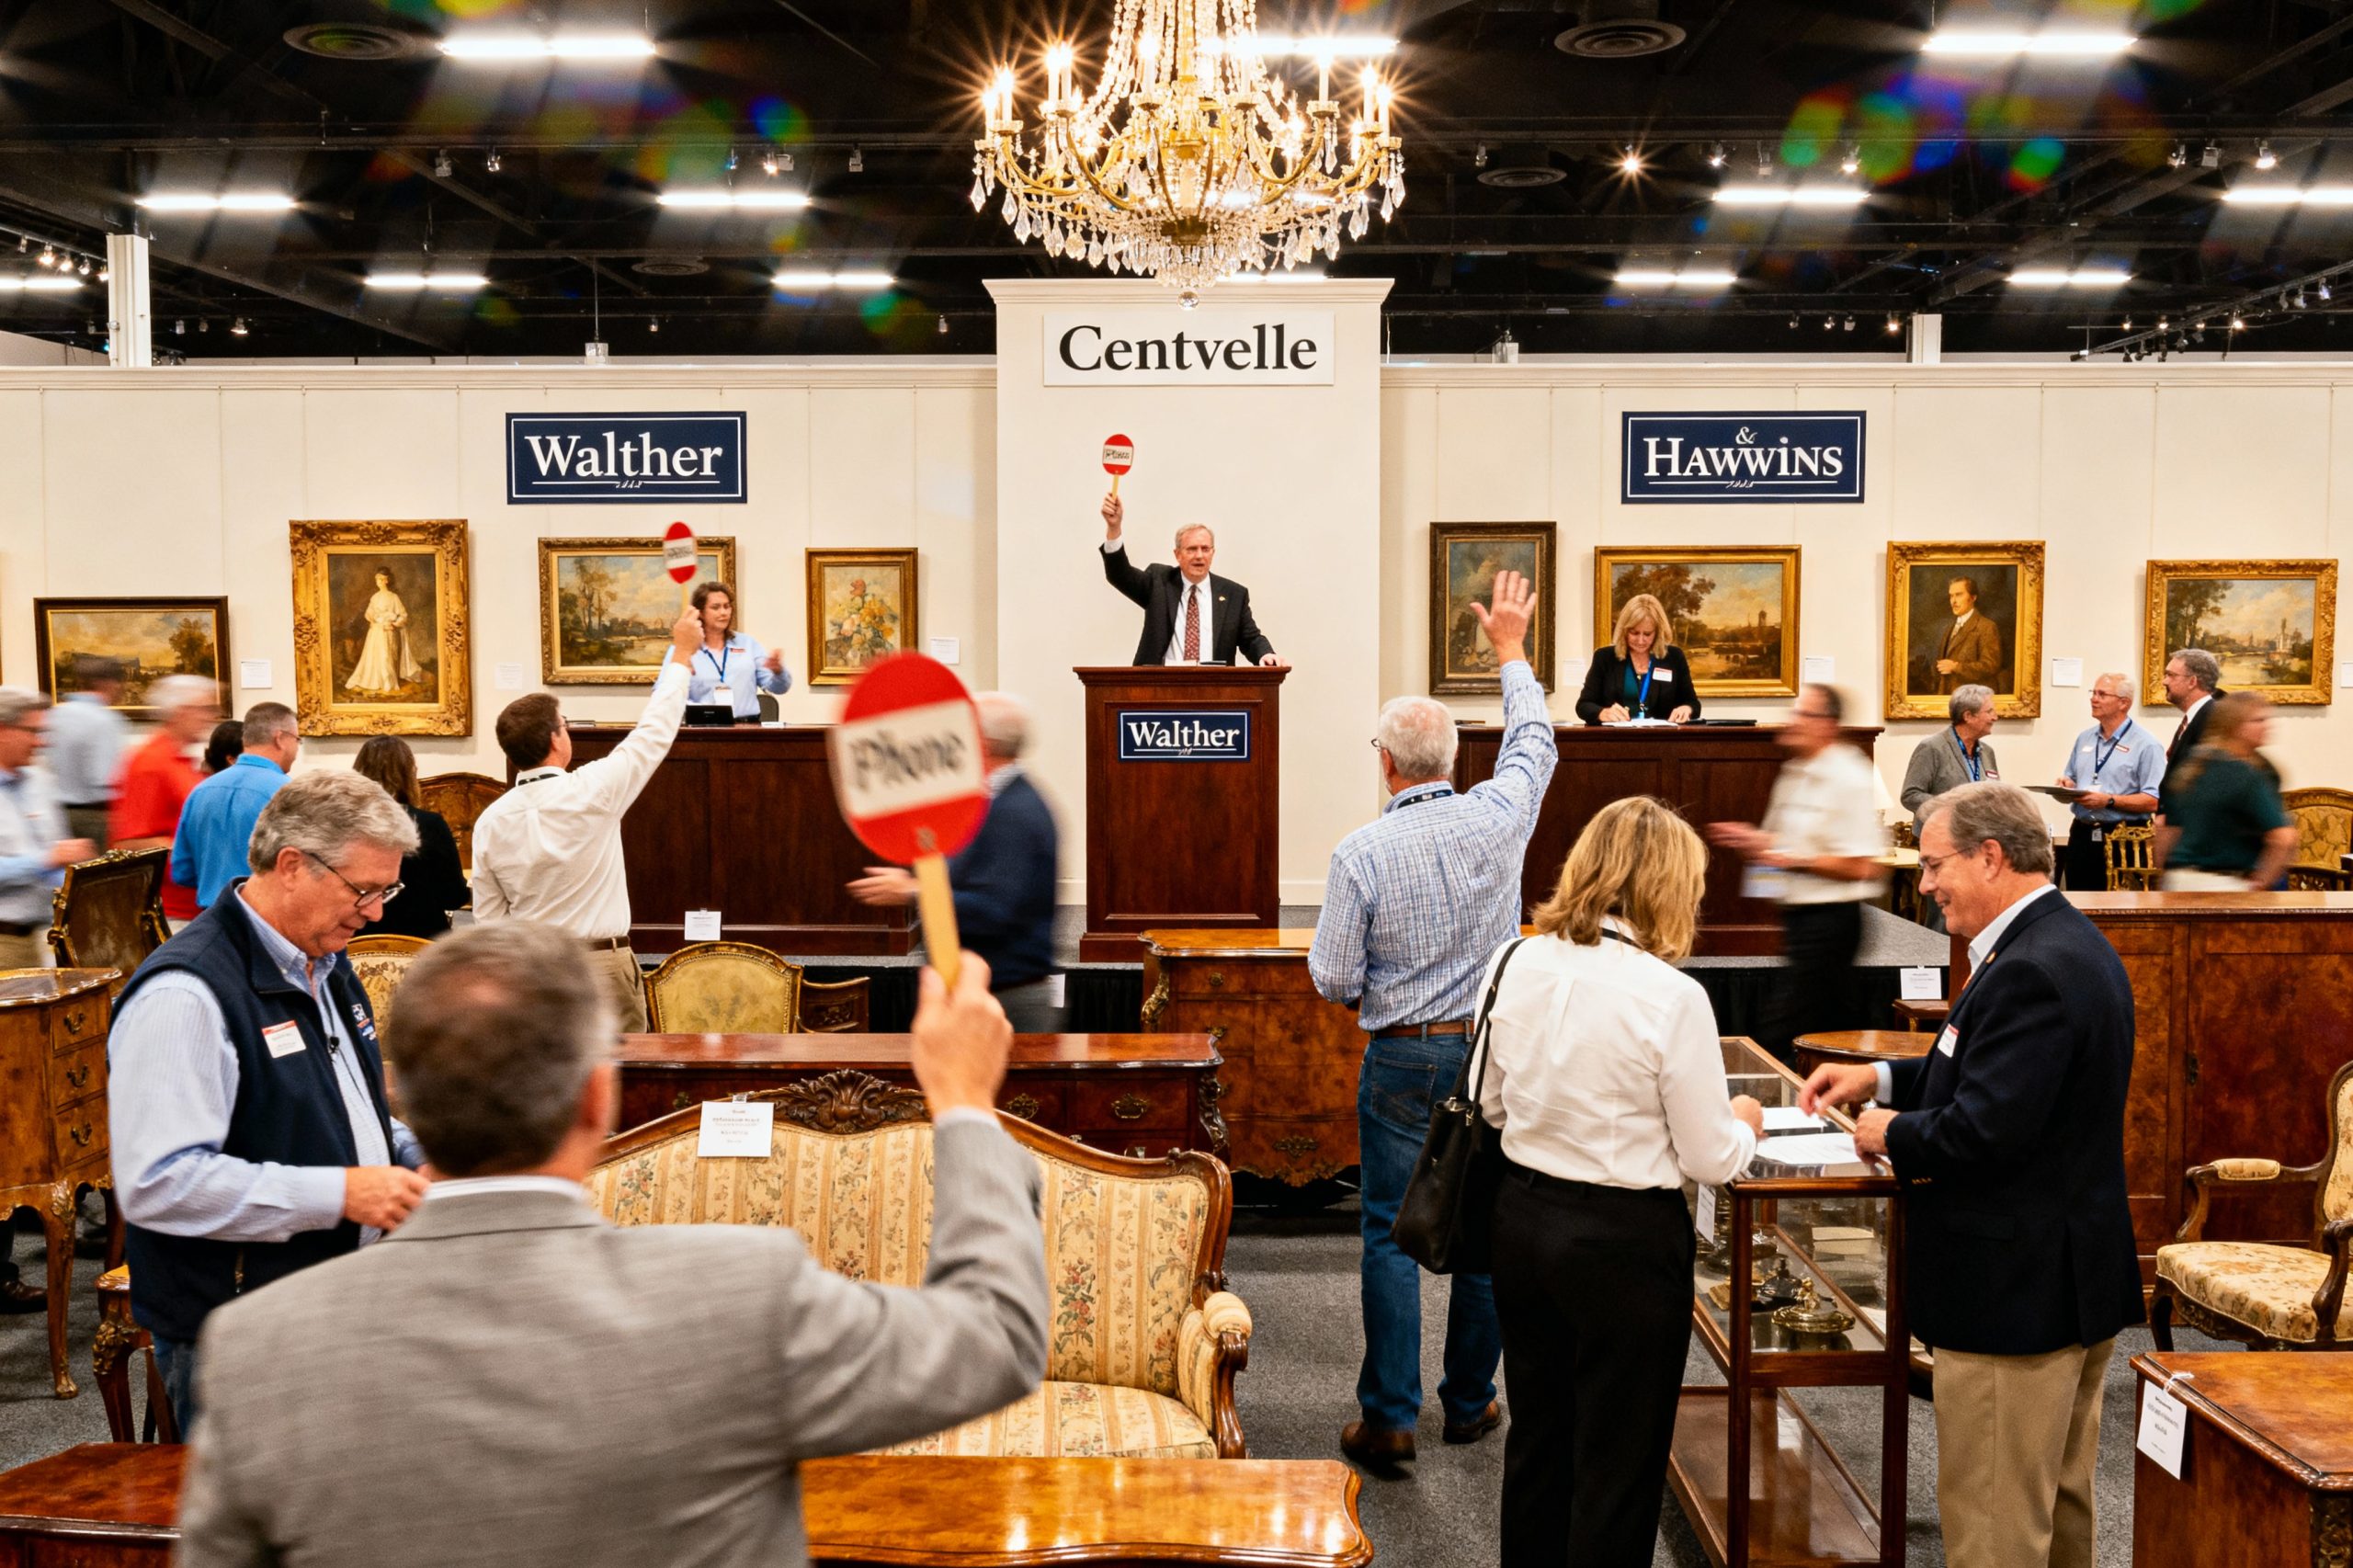
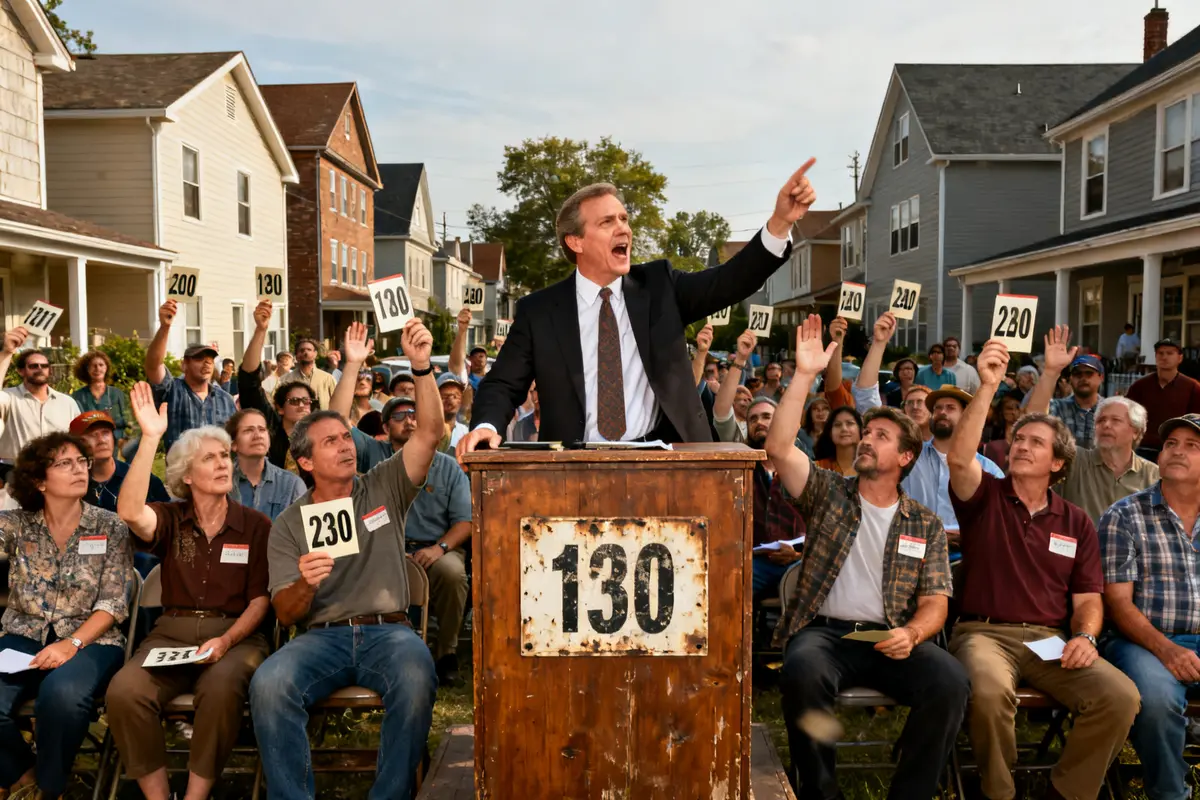
Once registered, bids begin at a set minimum, often the amount owed to the lender. Bidders compete live, with prices rising quickly. Winning requires staying alert and knowing your maximum bid beforehand. Payment must be made promptly, usually within 24 to 48 hours after the auction closes. Failure to pay results in forfeiture of the deposit and may lead to legal consequences.
Post-Sale: Deed Transfer and Redemption
After the sale, the winning bidder receives a certificate of sale, but the actual deed transfer might not happen immediately. Many states offer a redemption period that lasts from 30 days up to 12 months, during which the original owner can reclaim the property by paying the full debt plus costs.
This stage is critical to understand because ownership may not be guaranteed immediately. If redemption occurs, your purchase funds are refunded, but you lose the property. Only after the redemption period expires does the deed transfer or trustee’s deed finalize ownership to the buyer. Planning for this timeline is essential for managing expectations and financial arrangements.
Thorough Due Diligence Before Bidding
Title and Liens Check
Before bidding, always conduct a thorough title search. Foreclosed homes might carry hidden liens, unpaid property taxes, or legal judgments that transfer with the deed. Some junior liens may survive the foreclosure, so they become the responsibility of the new buyer. Using a title company or professional service ensures you identify all encumbrances ahead of time. This protects you from unexpected costs and legal battles after purchase.
Property Condition and Inspections
Foreclosed properties are sold strictly « as-is, » which means there are usually no warranties or seller disclosures. Access for inspections is often limited or denied. However, doing a careful visual inspection or hiring a licensed home inspector, if permitted, can reveal costly repairs or safety issues. Some buyers also check public records for code violations or previous damage claims that indicate the property’s condition.
Occupancy and Risk Assessment
Checking whether the home is occupied is crucial. Some foreclosure properties still have tenants or even the former owner living inside. Eviction and securing property can be expensive and time-consuming. Assessing this risk beforehand allows you to budget for legal eviction processes or adjust your timeline for taking possession. Risk assessment also includes considering local market conditions and profit potential to ensure your investment is sound.
Author’s Note
« Understanding the complete auction timeline and the redemption window is essential before placing a bid to avoid costly surprises after the sale. »
Financing, Legal Protections, and Fast Closings
Get Pre-Approval and Cash Readiness
Successful bidding requires having your financing lined up in advance. Many foreclosure auctions require bidders to pay in full or provide a substantial deposit immediately after winning. Most auctions expect cash payments or cashier’s checks; loans or financing contingencies are rarely accepted.
Getting pre-approved for a mortgage or arranging cash reserves ensures you’ll be ready to close quickly. Keep in mind that the deposit at registration, often 5% to 10% of the price, is non-refundable. If you cannot complete payment within 48 hours, you will lose your deposit and risk being banned from future auctions.
Engage a Real Estate Attorney for Documentation
Legal complexities are part of foreclosure auctions. Documents like the notice of sale, certificate of sale, and deed transfers require expert attention. Having a real estate attorney review all auction paperwork guards against procedural errors, missed timelines, or hidden liens.
An attorney can also help you understand state-specific laws about redemption periods, eviction rights, and title clearing. This legal guidance is an invaluable layer of protection to reduce risks and confirm that your purchase is solid and enforceable.
Finding Listings and Evaluating Deals
Locating foreclosure auctions requires using multiple sources. Government and county websites often post legal notices and auction schedules. Private websites, including online marketplaces, aggregate thousands of foreclosed property listings nationwide.
Working with real estate agents familiar with distressed sales can speed your search and provide insights about neighborhoods, title issues, and auction requirements. When evaluating deals, factor in the property’s location, estimated repair costs, and potential liens to gauge true value.
Key tips for evaluating foreclosure listings:
- Check auction terms and registration deadlines carefully
- Review recent sales in the area for price comparison
- Estimate renovation costs conservatively
- Consider risks like occupancy, title problems, and redemption timelines
💰 Foreclosure Auction Bid Calculator
Use this calculator to estimate your maximum bid price based on your budget, deposit requirement, and repair costs.
Redemption Periods, Risks, and Timelines
After winning a foreclosure auction, buyers face a key waiting period called the redemption period. This time frame varies by state, typically lasting from 30 days to 12 months, during which the previous owner can repay the full debt and reclaim the property.
Because of this, buyers are not guaranteed immediate ownership and should prepare for delayed possession. If the owner redeems, buyers receive a refund but lose the property, requiring careful financial and strategic planning.
There are also risks such as hidden liens, structural issues, and occupancy complications that come with buying foreclosures. Every sale is "as-is," so buyers assume responsibility for repairs and legal clearances afterward.
The timelines involved in foreclosure auctions demand careful monitoring of notices, deadlines, and local laws. Fast closings are possible only after all legal requirements and redemption windows have ended.
Key risks to assess before bidding:
- Possibility of liens or unpaid taxes surviving the sale
- Unknown property damage or maintenance costs
- Redemption period delaying full ownership
- Potential eviction of occupants
- Strict payment and auction rules that require exact timing
Understanding these risks and timelines can help you bid confidently and avoid costly surprises in the process of buying foreclosure homes.
FAQ — how do foreclosure auctions work
Is buying a foreclosed home on auction risky?
Buying a foreclosed home at auction carries risks such as hidden liens, unknown property damage, redemption periods delaying ownership, potential occupant eviction, and strict payment rules. Buyers must conduct due diligence and be prepared for these challenges to avoid costly surprises.
How much less do foreclosed homes sell for at auction?
Foreclosed homes often sell for less than market value due to their "as-is" condition, potential liens, and risks involved. Discounts vary widely depending on location, property condition, and auction competition, making thorough evaluation crucial before bidding.
What are the pros and cons of buying a foreclosed home?
The pros of buying a foreclosed home include lower purchase prices and investment opportunities. Cons include buying "as-is" without warranties, possible liens, limited inspection access, redemption periods, and potential occupant eviction costs.
What should I know before bidding at a foreclosure auction?
Before bidding, understand auction timelines, registration requirements, deposit rules, and payment deadlines. Conduct title searches, inspect the property if possible, assess occupancy status, and prepare finances since payments are often required in cash and quickly after winning.
How do foreclosure auctions work in California?
Foreclosure auctions in California start with a notice and set timeline. Bidders must register with a deposit and bid live starting at the owed amount. After winning, there's a redemption period allowing the original owner to reclaim the property. Deed transfer happens after redemption ends.
How do foreclosure auctions work in Texas?
In Texas, foreclosure auctions begin after a notice is issued with a timeline leading to auction day. Bidders register with a deposit and compete starting at the lender's owed amount. After the auction, a redemption period may apply, during which the previous owner can reclaim the property.
John has been passionate about furniture and interior design for over a decade, combining his love for vintage pieces with modern styling techniques. After years of helping friends transform their spaces and restoring countless furniture finds, he started this blog to share his expertise and inspire others to create homes they truly love. When he’s not writing or hunting for unique pieces at estate sales, you’ll find him refinishing a mid-century dresser or experimenting with new room layouts in his own ever-evolving home.